
🛒 Where to Buy: Business Travel Luggage
- Samsonite Freeform Hardside Expandable Luggage: View on Amazon
Click the link above to check current pricing, availability, and customer reviews on Amazon.
Editorial Note & Product Verification: The Cool Great Buys editorial desk independently verifies manufacturer technical specifications, cross-checks active retail availability across authorized sellers, and evaluates verified consumer reliability data before publishing product evaluations. All featured prices and promotions reflect active market rates at the time of publication.
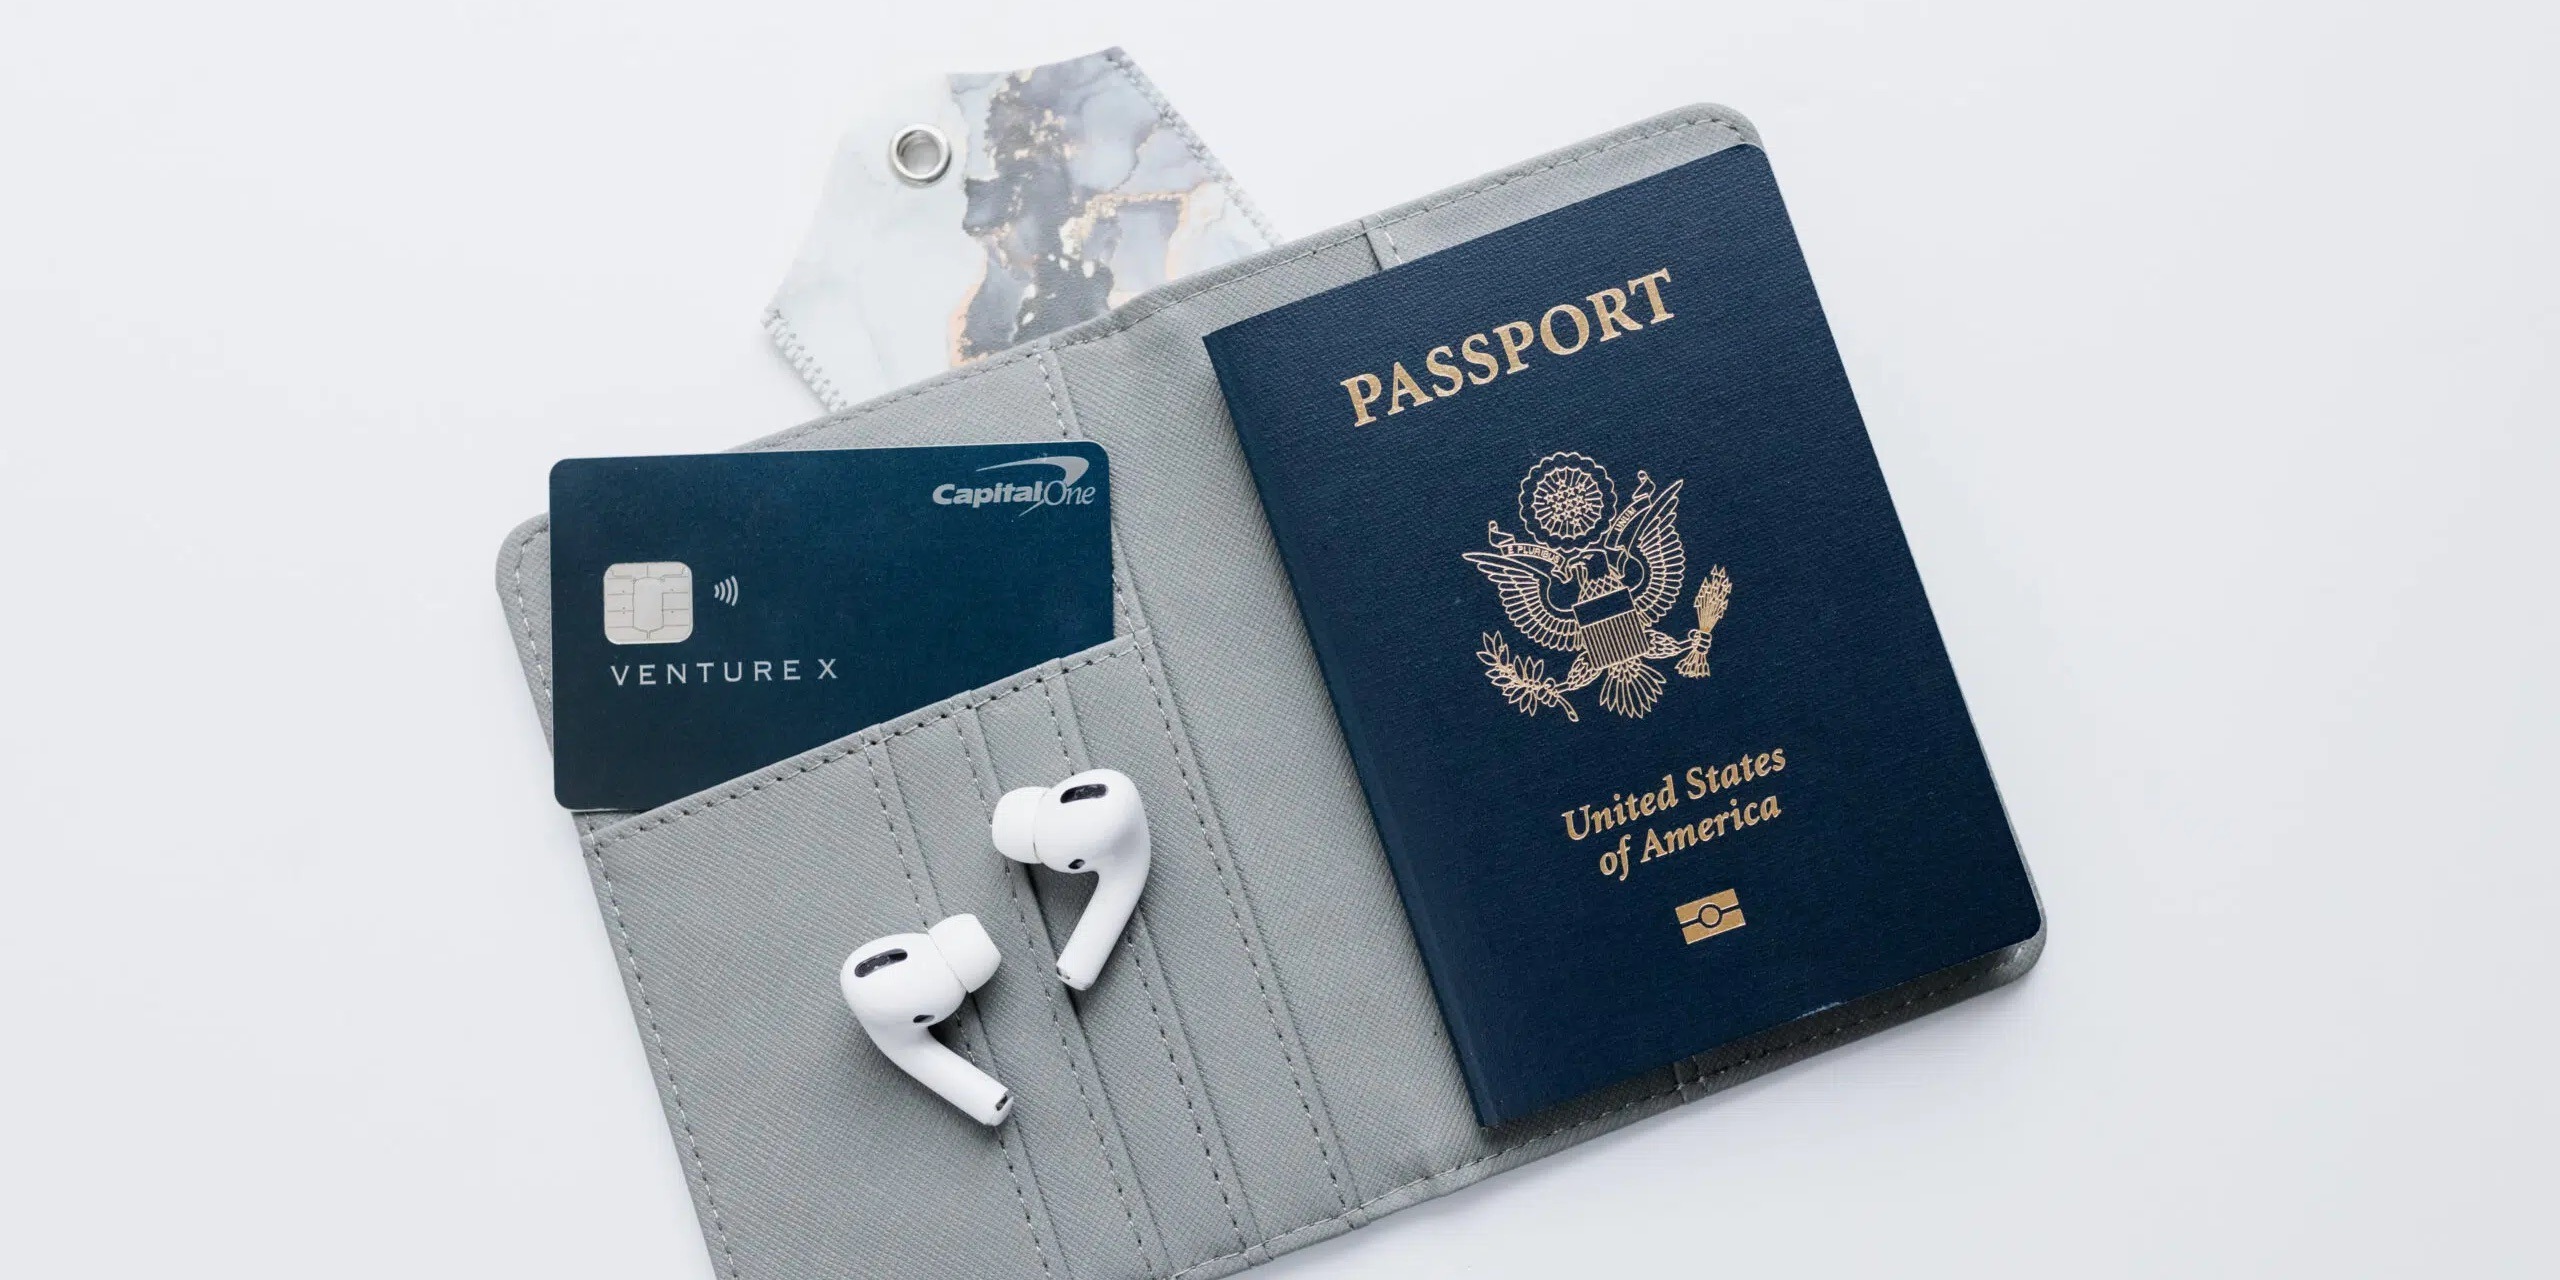
The Capital One Venture X Rewards Credit Card is a premium metal Visa Infinite credit card designed to earn transferable travel rewards and provide airport lounge access. It carries a $395 USD annual fee direct from Capital One. It is engineered for frequent travelers seeking to consolidate points across multiple accounts to secure high-value accommodation and flight redemptions. Initial product disclosures and reporting were tracked via Thriftytraveler.
Upfront Investment & 2-Year Total Cost of Ownership
Evaluating a premium financial product requires a cold, mathematical assessment of its ongoing carrying costs against its guaranteed yields. The Capital One Venture X Rewards Credit Card demands an upfront annual fee of $395 USD, billed on the first statement. Over a standard two-year holding period, the raw capital outlay totals $790 USD. For travelers seeking a lower entry point, the standard Capital One Venture Rewards Credit Card presents an alternative with a $95 USD annual fee, resulting in a two-year outlay of $190 USD. Notably, the distinction between these two tiers lies not just in their upfront pricing, but in how their respective benefit structures offset the initial investment.
In practice, the premium Venture X card features a highly structured rebate system that substantially lowers the net cost of ownership. Each year, cardholders receive a $300 USD credit for bookings made through the proprietary Capital One Travel portal. Additionally, starting on the first anniversary of account opening, the account is credited with 10,000 bonus miles, valued at a baseline of $100 USD when redeemed directly for travel statement credits. Over a two-year cycle, these structured offsets yield $600 USD in portal credits and 20,000 miles (worth $200 USD). Consequently, the total two-year net cost of ownership resolves to a negative $10 USD, assuming the cardholder naturally spends at least $300 USD annually on travel bookings.
Historically speaking, early iterations of premium travel cards often relied on highly fragmented, difficult-to-use credits to justify their high annual fees. Many legacy products required navigating monthly statement credits for specific ride-sharing services or highly restricted airline incidental fees that often went unused. The Capital One structure is notably more straightforward, though it does require the cardholder to route their travel spending through a specific booking channel to realize the value. For those unwilling to use a third-party portal, the standard Venture Card at $95 USD may represent a more predictable, low-friction path, even without the premium lounge benefits and anniversary bonuses.
What You Actually Get: Core Features & Build Specs
The physical manifestation of the Venture X is a precision-crafted, 17-gram metal card issued on the Visa Infinite network. This network designation grants access to primary rental car collision damage waivers, trip cancellation insurance, and cell phone protection. The core earning engine of the card is remarkably simple: it accrues a flat 2x miles per dollar spent on all everyday purchases, removing the cognitive load of tracking rotating category bonuses. For bookings made directly through the Capital One Travel portal, the earning rates escalate to 10x miles per dollar on hotels and rental cars, and 5x miles per dollar on flights.
The true utility of these accumulated miles lies in their transferability. Capital One provides direct access to 20-plus airline and hotel transfer partners, allowing cardholders to convert their points into partner loyalty currencies, often at a 1:1 ratio. However, the most compelling and historically unique feature of the Capital One miles ecosystem is the ability to transfer miles directly to any other Capital One cardholder. Unlike competing banking institutions that restrict points pooling to immediate family members residing at the same physical address, Capital One permits the transfer of miles to any individual, regardless of their relationship or residency status, completely free of charge.
This unrestricted sharing mechanism is highly advantageous for coordinating group travel and securing large accommodation bookings. For instance, a group of friends planning a vacation can pool their miles into a single account to cover the cost of an Airbnb using the Capital One purchase eraser feature, which allows miles to be redeemed at a flat rate of 1.0 cent per mile against recent travel purchases. Alternatively, miles can be consolidated into one member’s account to book high-value hotel award nights through transfer partners such as Wyndham Rewards or Choice Privileges. This level of flexibility is unmatched in the current consumer credit landscape.
Hidden Costs, Ecosystem Dependencies & Fine Print
While the unrestricted transfer policy is highly generous, it is accompanied by specific operational constraints that are frequently buried in the fine print. The most notable limitation is that cardholder-to-cardholder transfers cannot be executed online through the standard mobile app or web portal. Instead, the sender must place a phone call to Capital One customer service. According to official program documentation, the representative requires the recipient’s full name and their 16-digit Capital One card number to complete the transaction. While these phone calls are typically resolved in under five minutes and the miles transfer instantly, this manual requirement represents a deliberate friction point designed to mitigate fraud.
There is also a strict ecosystem dependency regarding the types of accounts involved in the transfer. The recipient must hold a card that actively participates in the Capital One rewards program, such as the Venture, Venture X, or Spark Miles series. If a recipient only holds a cash-back card, such as the Capital One Savor series, the transfer of miles is generally restricted or converted at a less favorable rate. Furthermore, relying on the Capital One Travel portal to utilize the annual $300 USD credit introduces an opportunity cost. Booking hotels through a third-party portal typically means forfeiting elite status recognition, in-property benefits, and loyalty points accrual with major hotel chains like Marriott, Hilton, or Hyatt.
Additionally, the long-term value of transferable miles is always subject to the risk of partner devaluations. While a transfer rate of 1:1 to programs like British Airways Executive Club or Avianca LifeMiles is highly valuable today, those programs can alter their award charts without prior notice. Historically, when banks make it incredibly easy to pool points, the underlying loyalty programs eventually adjust their redemption rates upward to compensate for the increased velocity of points entering their systems. Cardholders must therefore resist the urge to hoard miles indefinitely, adopting a “earn and burn” strategy to protect their purchasing power.
Smarter Alternatives at This Price
For consumers evaluating this space, the Chase Sapphire Preferred Card represents a formidable alternative, retailing for a modest $95 USD annual fee direct from Chase. The Sapphire Preferred earns Ultimate Rewards points, which can be transferred to highly lucrative accommodation partners, most notably World of Hyatt. However, Chase enforces a much stricter points-sharing policy. You are only permitted to combine points with one designated member of your household who is also an authorized user on your account. Attempting to transfer points to friends, extended family, or individuals outside your household can result in immediate account closure and the forfeiture of all accumulated rewards.
Another competitor in the premium tier is the American Express Gold Card, which carries a $325 USD annual fee direct from American Express. The Gold Card is highly regarded for its 4x earning multipliers on dining and US supermarkets, but its points-sharing capabilities are exceptionally restrictive. American Express strictly prohibits the direct transfer of Membership Rewards points from one cardholder’s account to another. The only viable workaround is to add the desired recipient as an authorized user on your account, wait a mandatory 90 days, and then transfer your points directly into that authorized user’s frequent flyer or hotel loyalty program account. This multi-step process is highly inefficient compared to Capital One’s direct model.
The trade-off between these systems ultimately comes down to transfer partner quality versus transfer flexibility. Chase offers superior domestic partners and unmatched value through Hyatt, but restricts your ability to collaborate with others. American Express offers powerful earning multipliers but locks your points down to your individual profile. Capital One occupies a unique middle ground: it provides a flat, uncomplicated earning structure and unmatched sharing flexibility, though its direct domestic hotel transfer partners are generally considered less prestigious than Chase’s exclusive partnership with Hyatt.
Final Buyer Verdict: Is the Investment Worth It?
The Capital One Venture X Rewards Credit Card is an exceptionally well-engineered financial tool for travel partners, families, and organized groups who actively coordinate their vacation planning. The ability to pool miles instantly and without cost across completely separate accounts transforms how group accommodations and flights can be booked. When combined with the straightforward 2x earning rate and the easily recoupable annual credits, the card represents a highly logical addition to the wallet of any traveler who comfortable utilizing booking portals to offset their upfront fees.
Conversely, the card is less suited for solo travelers who prefer to book their accommodations directly with hotels to maintain elite status benefits, or those who find the manual requirement of calling customer service to transfer miles to be an unacceptable digital-era friction. If your primary goal is securing luxury hotel stays specifically through the World of Hyatt program, the Chase ecosystem remains the superior choice despite its rigid sharing rules. For those who value simplicity, flexibility, and the democratic sharing of travel rewards, the Venture X stands as an unparalleled industry benchmark in 2026.